Choosing between FHA and Conventional loans? Compare down payments, credit requirements, mortgage insurance, and total costs to find the best mortgage for your situation.
Lower credit scores Minimal down payment Higher debt ratios
Good credit (700+) 10%+ down payment Loans above the county’s FHA limit (conforming or jumbo, by county and loan size)
2026 Loan Limits in New Jersey: FHA vs Conventional by County
Which loan can be larger depends on the county. In 12 of New Jersey’s 21 counties, Bergen among them, a one-unit FHA loan can be larger than a conforming conventional loan in 2026: $1,249,125 against $1,209,750. In the other 9, the conforming limit is the higher one.
•Can go past the FHA limit: up to $832,750 as a conforming loan in the 9 counties where the conforming limit is the higher one, and above the conforming limit as a jumbo loan (Bergen’s 2026 limits: FHA $1,249,125, conforming $1,209,750)
You had a bankruptcy or foreclosure within the past 3 years
Your loan amount fits your county’s FHA limit ($1,249,125 for one unit in Bergen County in 2026)
You don't plan to stay in the home long-term (less than 5 years)
Choose Conventional if:
Your credit score is 700 or higher
You have 10-20% for a down payment
You want to cancel mortgage insurance after reaching 20% equity
Your loan is larger than your county’s FHA limit (in Mercer County, anything over $541,287 for one unit in 2026)
You're buying a condo or investment property
You plan to stay in the home long-term (10+ years)
Buying a Condo in Bergen or Hudson After the 2027 Condo Rules
Short answer: with a condo, the building has to qualify, not just you. An FHA loan needs the building on HUD’s approved list, or a Single-Unit Approval. A conventional loan needs the building to meet Fannie Mae’s or Freddie Mac’s project rules; lenders call that a warrantable condo. A building that meets neither is non-warrantable, and only a lender that keeps or privately sells the loan can finance it, on its own terms.
Two conventional changes make that check matter more now. For loan applications dated on or after August 3, 2026, the lighter review many established buildings used (Fannie Mae’s Limited Review, Freddie Mac’s Streamlined Review) is gone. And for applications dated on or after January 4, 2027, a building must budget at least 15% of its assessment income to reserves, up from 10%. If you’re shopping high-rises in Fort Lee or Edgewater, or converted buildings in Hoboken and Jersey City, find out which group your building is in before you bid. The rules below were read at each agency’s own document on October 31, 2026.
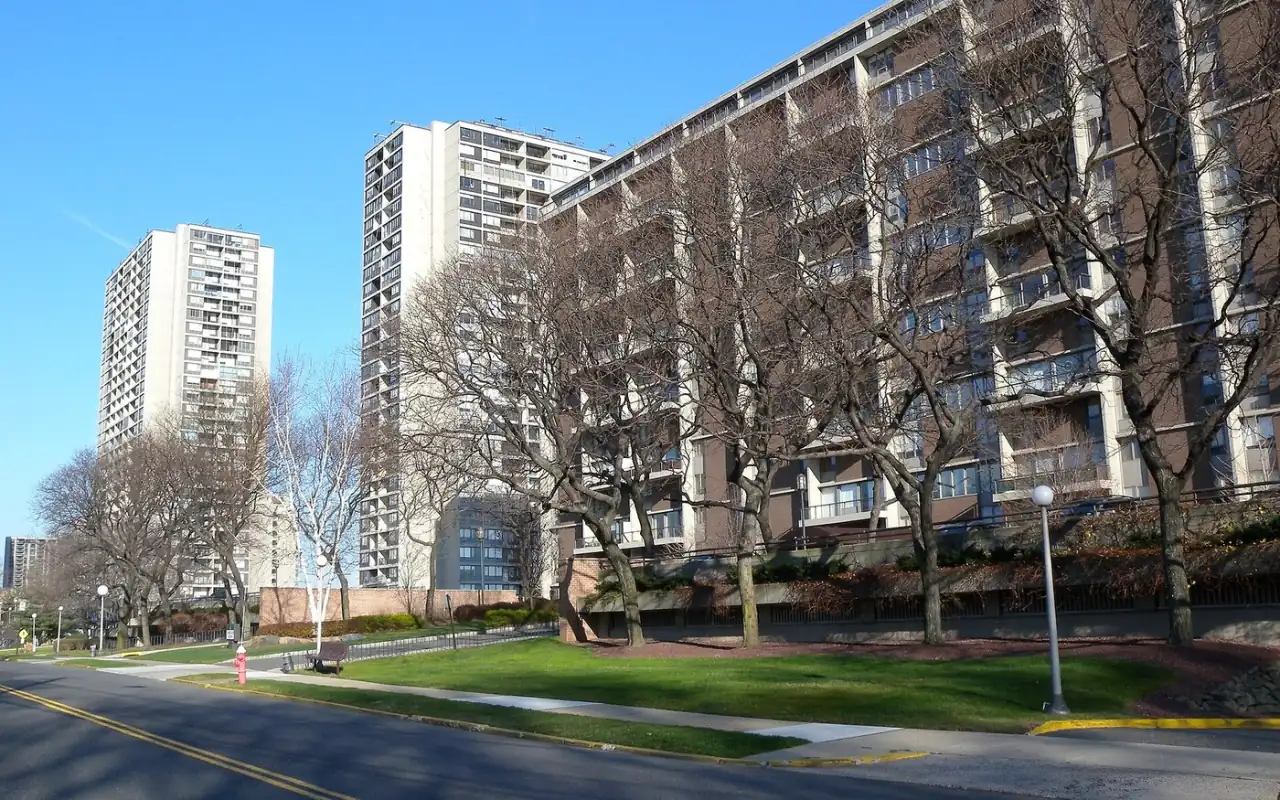
High-rise housing on Horizon Road, Fort Lee, Bergen County. Shown for illustration only; we have not checked these buildings’ FHA or conventional status. Photo: Jim.henderson, via Wikimedia Commons, CC0.
Three kinds of condo building, and the loan each one allows
1. FHA-approved (or approved one unit at a time)
The lender must confirm the building is on FHA’s approved list when it orders the FHA case number. If it isn’t, a Single-Unit Approval can still work when the building:
is complete, with at least 5 units, and isn’t a manufactured home;
has a certificate of occupancy for your unit issued at least one year ago, or the unit has been lived in;
is at least 50% owner-occupied;
doesn’t have too many FHA loans already: in a building of 20 or more units, FHA can stop new case numbers once more than 10% of units have one; under 20 units, the limit is 2 FHA loans;
funds reserves with at least 10% of 12 months of assessments (or a reserve study supports less), and no more than 15% of units are behind on dues.
Your file also has to get an Accept from FHA’s TOTAL scorecard, or stay at or under 90% loan-to-value if it’s underwritten by hand. In the current handbook (Update 18, August 2026), FHA’s reserve minimum is still 10%.
2. Warrantable: meets Fannie Mae or Freddie Mac rules
Full review for established buildings. For applications dated on or after August 3, 2026, established buildings get Fannie Mae’s Full Review or Freddie Mac’s established-project review.
Reserves: 10% today, 15% from January 4, 2027. The budget’s allocation for capital repairs and deferred maintenance must reach 15% of annual budgeted assessment income for applications dated on or after January 4, 2027. A reserve study can stand in, but from August 3, 2026 the budget has to fund the study’s highest recommended amount, not the “baseline” minimum.
Small buildings may skip the review. Both agencies now waive the project review for buildings of 10 or fewer units. A 5- to 10-unit building can’t be part of a master association, and Fannie Mae also rules out one inside a larger development.
Investor loans: Fannie Mae retired its 50% investor-concentration limit for investment-property loans in established buildings under Full Review.
A loan on a non-warrantable condo can’t be sold to Fannie Mae or Freddie Mac, so the lender that makes it sets the down payment, documents and pricing. From January 4, 2027, one way a building lands here is a reserve budget under the 15% line with no reserve study to back it. Fannie Mae can also mark a building “Unavailable” in its Condo Project Manager tool, which rules out its project-review waiver. Knowing this before you bid lets you decide whether that building still fits your budget, or whether to keep looking.
The 2027 reserve rule in numbers
Picture a building that collects $1,200,000 a year in assessments and budgets $140,000 of it for reserves (11.7%). Both numbers are made up for illustration.
Conventional, application dated before January 4, 2027: the minimum is $120,000 (10%), so the budget passes.
Conventional, application dated on or after January 4, 2027: the minimum is $180,000 (15%). The budget is $40,000 short, so the building needs a reserve study that supports its funding, or it fails.
FHA: the minimum stays $120,000 (10%), so this part of the review still passes.
The date that counts is your loan application date, not your closing date. Refinancing instead? A Fannie Mae-to-Fannie Mae limited cash-out refinance at 80% loan-to-value or less can skip Fannie Mae’s project review, if the building isn’t marked “Unavailable” in Fannie Mae’s Condo Project Manager and, in a building with more than 10 attached units, has no unaddressed critical repairs or evacuation orders (Selling Guide B4-2.1-02). Condo owners can read more in our New Jersey condo refinance guide.
Before you bid: what to get about the building
The building’s legal name and address, then its status on HUD’s condo search if you might use FHA.
The association’s current budget. Divide the reserve contribution by total assessment income: 15% or more clears the 2027 conventional line, 10% clears FHA’s.
How many units the building has, how many are owner-occupied, and how many owners are behind on dues.
Call Jimmy Joseph, MBA (NMLS #1577754) with the building’s name and address. He can check it against HUD’s list and the Fannie Mae and Freddie Mac rules for your loan before you’re under contract.
“Start your secure application” opens CMG’s secure application in a new tab. Calling first with the building name lets Jimmy look at the building before you apply.
While FHA requires less upfront cash ($17,500 vs $50,000 down), the lifetime mortgage insurance costs $61,560 more over 30 years. If you can afford 10% down and have good credit, Conventional saves significantly long-term. However, if you need minimal down payment, FHA gets you into a home sooner.
FHA in the Bergen Towns Near Paramus
These pages work through FHA for one Bergen town each, from HUD’s condo list, New Jersey’s 2025 property tax figures and Census data for that town.
What is the main difference between FHA and Conventional loans?
The main difference is that FHA loans require only 3.5% down with a 580 credit score, while Conventional loans typically require 5-20% down with a 620+ credit score. FHA loans have upfront and monthly mortgage insurance, while Conventional loans only require PMI if you put down less than 20%.
Which is cheaper: FHA or Conventional loan?
It depends on your down payment and credit score. With 10%+ down and good credit (700+), Conventional is usually cheaper because you can cancel PMI at 20% equity. With minimal down payment (3.5-5%) or lower credit scores, FHA may be more affordable initially despite lifetime mortgage insurance.
Can I cancel mortgage insurance on an FHA loan?
FHA loans with less than 10% down have mortgage insurance for the life of the loan. The only way to remove it is to refinance to a Conventional loan once you have 20% equity. FHA loans with 10%+ down can cancel MIP after 11 years.
What credit score do I need for FHA vs Conventional?
FHA loans accept credit scores as low as 580 (or 500 with 10% down). Conventional loans typically require a minimum 620 credit score, with better rates available at 700+. Higher credit scores qualify for better interest rates on both loan types.
Will my condo building still qualify for a conventional loan in 2027?
Only if it meets Fannie Mae's or Freddie Mac's project rules. For loan applications dated on or after January 4, 2027, the building's budget must put at least 15% of its annual assessment income into reserves, up from 10%, unless a reserve study supports the amount. The lighter Limited Review and Streamlined Review options ended for applications dated on or after August 3, 2026. FHA's own reserve minimum stays at 10%. See the condo rules, with sources.
Can I switch from FHA to Conventional later?
Yes! Many borrowers start with an FHA loan to buy with minimal down payment, then refinance to a Conventional loan once they have 20% equity and improved credit. This eliminates the lifetime mortgage insurance and can save thousands per year.
Which loan is better for first-time homebuyers?
It depends on your financial situation. If you have limited savings and lower credit (580-680), FHA is often better because of the 3.5% down requirement. If you have 10%+ saved and good credit (700+), Conventional will save you money long-term. We can run both scenarios to show you the exact costs.
Still Not Sure Which Loan is Right for You?
Get a personalized analysis comparing FHA vs Conventional based on your exact credit score, down payment, and home price. We'll show you which option saves you the most money.