Newton REALTOR® and buyer guide
Looking for a Newton, NJ REALTOR®? Start with Ashley Davidson
Search current homes with Ashley, then verify whether each result is truly in the Town of Newton and whether its property type and legal use match the listing. Ashley leads the real estate search, showings, property questions, and offer strategy; Jimmy tests financing, cash, and deadlines against the selected home.
Ashley provides real estate brokerage services. When you have a price range or address, Jimmy Joseph provides the separate mortgage lane through CMG Home Loans · NMLS #1577754.
Featured Sussex County real estate professional
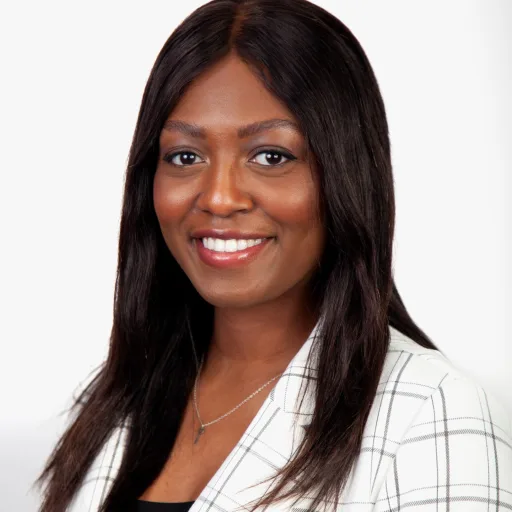
Ashley Davidson
REALTOR®, ABR®, MRP
Keller Williams Prosperity | Elevate Real Estate Group
Ashley helps Sussex County buyers and sellers compare communities, property types, transaction details, and the local professionals needed to move from a broad search to a property-specific decision.
Search current homes with Ashley ↗Check Ashley's public agent profiles
Third-party profile links are provided for identity and brokerage research; their content is controlled by those sites.
Ashley Davidson and Jimmy Joseph work through separate businesses. Ashley provides real estate brokerage services; Jimmy provides mortgage services. Each professional is responsible for their own services, and no lead, application, approval, or closing is promised.
Newton market check: September 14, 2026
Newton is the fastest-moving of the three Sussex towns
The county seat is small, in-town, and in demand. Realtor.com's Newton market page, read on September 14, 2026 with key indicators as of August 2026, shows homes going under contract in about a month and closing above asking, with far fewer listings than a year ago. That changes how a Newton buyer should prepare before the first showing.
- 34-day median time on market, down 46.43%. Newton listings sold almost twice as fast as a year earlier. Vernon's median was 62 days on the same Realtor.com indicators, Sparta's 35.
- Homes closed at about 104% of list. Realtor.com labels Newton a seller's market. Plan on competing offers for a well-kept in-town house, and have the pre-approval and inspection plan ready before you tour.
- Median list price $467,500, median sold price $442,250. List up 14.15% and sold up 8.53% from a year earlier. The gap between the two says new listings are coming on higher than what closed over the summer.
- 109 active listings, down 24.49%. Roughly half of Vernon's inventory in a much smaller town. A buyer with a narrow street or property-type target should expect to wait for the right listing rather than choose among several.
- $244 per square foot, down 22.45%. A falling per-square-foot figure alongside rising medians usually means larger or older homes made up more of the sales. Judge each house on its own comparables rather than on the town-wide rate.
- $1,772 median rent; ZIP 07860 median list $482,304. The 07860 ZIP code showed 108 homes for sale at a 31-day median on the same read. That ZIP reaches past the Town of Newton, which is why this guide keeps asking you to confirm the municipality on the tax record.
Property taxes: Newton's 2025 numbers from the state
- Average residential tax bill $9,001 on an average assessment of $338,127, about $750 a month, almost exactly the county average of $8,997.
- Effective rate 2.732 per $100 (general rate 2.662). That is the highest effective rate of the three towns in these guides, above Sparta's 2.347 and Vernon's 2.310, so a Newton house carries more tax per dollar of value even though the average bill is lower than Sparta's.
- 34 usable residential sales at a $404,440 average in the state's 2025 table, the smallest sample of the three towns. Small samples move quickly, which is another reason to price from a handful of true comparables.
Sources: NJ 2025 general tax rates ↗ and NJ 2025 average residential statistics ↗, read September 14, 2026. Ask Ashley for the current tax record on any specific house.
Getting ready for a 34-day market
- Pre-approval first, then showings. In-town Newton houses can be under contract before a second weekend. Jimmy can issue a property-specific pre-approval so the offer goes in the same day you decide.
- Confirm the municipality before you fall for the house. Ashley checks the tax municipality and legal use on the county record, because a Newton mailing address can sit in a neighboring township with different taxes and schools.
- Plan the inspection for an older home. Newton's in-town stock includes many pre-war houses. Knob-and-tube wiring, older boilers, sewer laterals, and lead paint are common findings; decide in advance which ones you would walk away over.
- For a two- to four-family, verify the income. Ask for current leases, the certificate of occupancy, and the legal unit count before the lender counts rent toward qualifying; Realtor.com's $1,772 median rent is a town-wide figure, not the rent on a specific unit.
Schools: Realtor.com's Newton market page lists GreatSchools ratings of 3 for Merriam Avenue Elementary, 5 for Halsted Street Middle, and 4 for Newton High School, read September 14, 2026. Treat ratings as one input, and confirm the attendance zone for the address.
Market figures: Realtor.com Newton housing market ↗, key indicators as of August 2026, read September 14, 2026. See the county picture on the Sussex County guide, or compare Newton with Sparta and Lake Mohawk and Vernon.
More useful than another list of listings
Turn a Newton, NJ search result into a property decision
Large portals are useful for scanning inventory. This page adds the part a portal cannot finish for you: a direct path to Ashley, a local property-review framework, and a clean handoff to property-specific financing before an offer depends on it.
01
Search current homes
Open Ashley's team search, save realistic Newton, NJ candidates, and confirm availability before planning around a listing.
02
Pressure-test the property
Use Ashley's real estate guidance and this Newton, NJ decision map to surface ownership, condition, document, and offer questions.
03
Make the offer financeable
Give Jimmy the real address, price, taxes, property type, association details, and timing so the mortgage plan matches the offer.
Ready to move from browsing to a real shortlist?
Search first, then bring Ashley the addresses that deserve a property-specific conversation.
Property-to-mortgage handoff
Use Jimmy's tools after the home-search brief
Once Ashley has helped narrow the property lane, use these pages to test payment, loan fit, and the next mortgage step.
Local context first
Know which Newton, NJ purchase you are actually making
A Newton mailing address or portal label may not prove that a parcel sits within the Town of Newton. Confirm the tax municipality, school district, zoning, utilities, certificates, permits, and legal use for the exact address.
Town-center access, parking, property age, unit count, shared obligations, and renovation history can matter as much as square footage. Choose the property lane first, then compare relevant sales, financing, inspection scope, and cash reserves within that lane.
Town-center and older homes
Test the exact block for parking, road activity, errands, outdoor space, and daily routines. Match visible improvements to permits and inspect the systems behind cosmetic updates.
Condo and attached housing
Review association financials, reserves, insurance, assessments, maintenance responsibilities, rules, parking, rental policy, and lender project requirements early.
Multifamily and income claims
Confirm legal unit count, zoning, certificates, leases, expenses, utilities, insurance, appraisal treatment, and whether income may be used under the selected loan program.
Comparison framework
How to compare a mortgage broker, lender, bank, or loan officer
Search results mix several different business models. Compare the person, company, program, property fit, full cost, and closing plan. Jimmy Joseph is identified on this site as a Loan Officer and mortgage loan originator with CMG Home Loans; the guide does not turn that role into an unsupported broker claim.
Role and licensing
Confirm whether you are speaking with a broker, lender, bank, credit union, or mortgage loan originator; verify licensing and ask which company is responsible for the loan.
Same-day cost comparison
Compare rate, points, lender credits, lender fees, mortgage insurance, and estimated cash to close on the same day and for the same loan scenario.
Program and property fit
A low quote is not useful if the program does not fit the borrower, property type, occupancy, condition, association, appraisal, or contract timeline.
Communication plan
Ask who answers after hours, who updates the agent and attorney, how quickly preapproval letters change, and how problems are escalated before deadlines.
Underwriting path
Understand what has actually been reviewed, which conditions remain, whether the file is automated or manually underwritten, and what can still change before closing.
No-pressure explanation
You should be able to understand the tradeoffs, disclosures, and next steps without a guarantee, artificial deadline, or promise that every buyer receives the same result.
Property checks that belong beside the preapproval
Financing and property due diligence are connected. A buyer can be financially qualified while the property, association, insurance, appraisal, title, or legal use still creates a problem. Bring the address into the mortgage conversation early.
Municipality and legal use
Verify the tax municipality, zoning, certificates, permits, and legal occupancy—especially near boundaries or when a listing suggests multiple units or finished space.
Older-home systems
Review structure, roof, drainage, electric, plumbing, heating, water, wastewater, environmental concerns, and renovation records with qualified professionals.
Parking and access
Confirm deeded or permitted parking, shared access, snow responsibilities, storage, entrances, and the daily practicality of the property rather than relying on listing language.
Association and shared costs
For condos or attached homes, include dues, assessments, insurance responsibilities, reserves, and project eligibility in both the monthly budget and loan review.
Appraisal and cash reserves
Older, mixed-use, or multifamily properties may need more exact comparable sales and documentation. Keep room for appraisal issues, inspections, and first-year repairs.
Offer-to-closing system
Six checkpoints for a financeable purchase
The goal is not to rush from lead to application. It is to make the next decision with enough verified information that the loan, property, and contract can reach the same closing table.
Step 1
Set the comfort number
Build a monthly and cash-to-close range that includes taxes, insurance, common charges, maintenance, transportation, and reserves—not just principal and interest.
Step 2
Review documents and credit
Provide complete, accurate documentation early enough to identify income, asset, credit, employment, gift, or property issues before an offer clock is running.
Step 3
Match the property
When a serious address appears, give the lender the listing, taxes, property type, association status, occupancy plan, and known condition so the preapproval still fits.
Step 4
Write a financeable offer
Coordinate lender, agent, and attorney dates for financing, inspection, appraisal, commitment, and closing. Speed should not erase protections you still need.
Step 5
Inspect, appraise, and underwrite
Track property condition, title, insurance, appraisal, borrower conditions, and association or municipal records as separate workstreams with named owners.
Step 6
Verify final cash and terms
Review the Closing Disclosure, final loan terms, verified wire instructions, walkthrough result, and remaining reserves before signing.
Budget beyond the down payment
Cash to close is a collection of categories, not one fee. The Loan Estimate and Closing Disclosure are the official transaction documents. Use early worksheets for planning, then reconcile the final numbers instead of assuming every estimate is fixed.
- •Down payment and any required reserves
- •Lender charges, points, and lender credits
- •Appraisal, credit, flood, tax, and other loan services
- •Attorney, title, survey, recording, and settlement charges
- •Prepaid interest, homeowners insurance, taxes, and escrow funding
- •Inspection, association, municipal, moving, repair, and setup costs
Loan paths to discuss—not assume
Program names do not decide fit by themselves. Compare eligibility, property standards, mortgage insurance or fees, appraisal, cash, reserves, occupancy, and the contract timeline.
Conventional financing
Worth comparing when borrower qualifications, down payment, property type, and mortgage-insurance tradeoffs fit. Condominium and appraisal requirements still matter.
FHA financing
May help some buyers with down-payment or credit flexibility, but property condition, appraisal standards, mortgage insurance, loan limits, and occupancy rules must fit.
VA financing
For eligible service members and veterans, compare entitlement, funding-fee treatment, property standards, appraisal timing, and the complete offer strategy.
NJHMFA and New Jersey programs
Official New Jersey programs may provide mortgage or down-payment support for eligible buyers. Current borrower, property, income, price, occupancy, counseling, and participating-lender rules control.
Questions to ask before choosing the mortgage path
Ask every mortgage professional
- 1.Which loan programs are you comparing for this exact scenario, and why?
- 2.What assumptions are built into the quote, and which numbers can change?
- 3.How are you and your company compensated on this transaction?
- 4.What has been reviewed for preapproval, and what still needs underwriting?
- 5.Which property types or conditions could make this program fail?
- 6.Who owns each deadline from application through closing?
Ask for this Newton, NJ property
- 1.Is the property in the Town of Newton or using a Newton mailing address?
- 2.Does the legal use match the way the listing describes every unit and finished area?
- 3.Which permits, certificates, leases, or association documents still need review?
- 4.Which older-home systems need specialist inspection or near-term capital?
- 5.Do the comparable sales match the same property type and municipality?
- 6.How do taxes, insurance, dues, repairs, and the proposed loan affect cash after closing?
Verify at the source
Official resources for your property file
Rules, records, maps, program limits, and eligibility can change. These links are starting points; the exact address, transaction, and current official record control.
Town of Newton ↗
Official starting point for tax, zoning, building, clerk, planning, and town-service information.
Sussex County: Newton Green ↗
Official Sussex County context for Newton's historic Green and county-seat setting.
Realtor.com Newton housing market ↗
Median list and sold prices, sale-to-list ratio, active listings, price per square foot, and days on market for Newton; key indicators checked September 14, 2026.
NJ Division of Taxation: 2025 General Tax Rates by municipality ↗
State table of 2025 general and effective tax rates for every Sussex County municipality; used for verification of the Newton rates on this page.
NJ Division of Taxation: 2025 Average Residential Assessment, Sales, and Taxes ↗
State table of 2025 average residential value, average tax bill, usable sales, and average sale price by municipality; source of the Newton and county-wide tax figures on this page.
NJHMFA homebuyer roadmap ↗
Current official New Jersey homebuyer-program, counseling, eligibility, and participating-lender guidance.
CFPB Home Loan Toolkit ↗
Federal guidance for comparing mortgages, understanding closing costs, and reviewing the Loan Estimate.
FEMA FloodSmart ↗
A starting point for checking flood risk and understanding flood-insurance questions for a specific address.
Choosing a Newton, NJ REALTOR®
What a Newton buyer needs from an agent in a seller's market
When the median listing goes under contract in 34 days and closes above list, the agent's job is speed with discipline: the right house identified quickly, the municipality and legal use verified before the offer, and a written agreement that says plainly what you are paying for.
Newton-specific questions
- How quickly can they confirm that a listing is in the Town of Newton, and what taxes and schools apply, before you tour?
- What is their approach to a competing-offer situation on an older in-town house: escalation terms, inspection scope, and appraisal gap?
- For multifamily, will they collect leases, the certificate of occupancy, and the legal unit count before the offer, not after?
- Which recent Newton sales would they use as comparables, and how do they adjust for a pre-war house against a newer one?
The agreement and the fee, in Newton dollars
- New Jersey's Real Estate Consumer Protection Enhancement Act, in force since August 1, 2024, requires a written brokerage services agreement and a consumer information statement at the start of the relationship.
- The National Association of REALTORS® practice changes, effective August 17, 2024, mean the buyer agreement is signed before touring and states the buyer-agent compensation.
- Commissions are negotiable. A combined 5% to 6% of the price has been common; at Newton's $442,250 median sold price, each 1% is about $4,423, a smaller absolute figure than in Sparta but still worth negotiating in writing.
- In a seller's market, fewer Newton sellers may offer to cover buyer-agent compensation; know before the offer whether you are carrying that cost.
Sources: NJ Real Estate Commission ↗ and NAR settlement facts ↗, read September 14, 2026.
Work with Ashley in Newton
Ashley Davidson, REALTOR®, ABR®, MRP, with Keller Williams Prosperity | Elevate Real Estate Group, works Newton and the rest of Sussex County. She separates true Town of Newton inventory from the wider 07860 mailing area, verifies legal use, and runs the search, showings, comparables, and offer. Jimmy Joseph handles the mortgage through his own business; the two lanes stay separate.
Mortgage lane
A 34-day market does not wait for a pre-approval. Have Jimmy issue one against a Newton price and tax bill before Ashley books the first showing.
Newton, NJ REALTOR® and home buyer FAQs
How can Ashley Davidson help a Newton, NJ home buyer?
Ashley can help narrow the Newton, NJ search, coordinate showings, compare property-specific facts and relevant sales, organize due-diligence questions, and lead the real estate offer process. Ashley and Jimmy work through separate businesses; Jimmy handles the mortgage lane.
Where can I search current Newton, NJ homes for sale?
Use the Search Current Homes link on this page to open Ashley's team search site. Listing availability changes continuously, so confirm status and property details with Ashley rather than treating this educational guide as an MLS or IDX feed.
What should I ask a Newton, NJ REALTOR® before making an offer?
Ask how the selected property compares with relevant sales, which facts and documents still need verification, what inspections or specialists may be appropriate, how contingencies protect the buyer, and who owns each deadline from offer through closing.
Is it cheaper to use a mortgage broker or a bank in Newton, NJ?
There is no universal winner. Compare the full Loan Estimate, rate and points on the same day, lender fees, third-party costs, mortgage insurance, program fit, service, and the professional's ability to meet your contract. Jimmy Joseph is a mortgage loan originator with CMG Home Loans; this page helps buyers compare the process without mislabeling every lender or loan officer as a broker.
What is the downside of using a mortgage broker or other mortgage professional?
Any channel can be a poor fit if costs are unclear, choices are not explained, communication is slow, or the professional cannot support the property and timeline. Ask who the person represents, how compensation works, which products are available, what is locked, and what could change before closing.
How is a mortgage broker or loan originator paid?
Compensation and fees vary by company and transaction. Ask for a clear explanation and review the official Loan Estimate and later Closing Disclosure. Do not rely on a verbal quote or assume that “no fee” means there is no economic cost.
What is the mortgage 3-7-3 disclosure timing rule?
The shorthand generally refers to federal timing around early loan disclosures, a minimum waiting period before consummation, and receipt of the Closing Disclosure before closing. Your actual calendar depends on the application, business-day definitions, changes, and transaction, so have the lender and attorney confirm your dates in writing.
How much are property taxes in Newton, NJ?
The state's 2025 table lists the Town of Newton at a 2.662 general tax rate and a 2.732 effective rate, the highest effective rate of the three Sussex towns on this site, with a $338,127 average residential assessment and a $9,001 average bill. That is almost exactly the Sussex County average of $8,997. Newton's average is built on only 34 usable 2025 sales at a $404,440 average price, so a specific address can sit well above or below it; pull the parcel record and run it through Jimmy's payment test.
How fast do Newton homes sell?
Fastest of the three Sussex towns. Realtor.com's Newton market page, checked September 14, 2026, showed a 34-day median time on market, down 46.43% from a year earlier, with homes closing at about 104% of list price, a $467,500 median list price, a $442,250 median sold price, and 109 active listings. In a market that short, a pre-approval with verified income and assets has to be finished before the first showing, not after the first offer.
Do I have to pay Ashley a fee to buy in Newton?
New Jersey's Real Estate Consumer Protection Enhancement Act has required a written brokerage services agreement before an agent works for a buyer since August 1, 2024, and the compensation in it is negotiable. On a $442,250 Newton median sale, each 1% is about $4,423. Settle the amount and whether the seller will be asked to cover it in the agreement before touring, then test the full cash-to-close with Jimmy.
Is Newton the county seat of Sussex County?
Yes. Sussex County identifies Newton as the county seat. Buyers should still confirm how a specific address fits their routes, services, parking, and property priorities.
Does a Newton mailing address mean the home is in the Town of Newton?
Not necessarily. Verify the tax municipality, school district, zoning, utilities, and property records instead of relying on the mailing city or a portal label.
Can I buy a multifamily home in Newton?
Inventory may include multifamily properties, but the legal unit count, zoning, certificates, leases, expenses, utilities, insurance, appraisal treatment, and financing must be verified for the exact address.
How can Ashley and Jimmy help a Newton buyer?
Ashley can separate true Town of Newton inventory from broader mailing-area results and coordinate the real estate process. Jimmy can review financing, cash, property eligibility, and deadlines. They work through separate businesses.
Is Newton an affordable way into Sussex County?
Often. Sussex County's overall market showed 1,009 homes for sale at a $434,999 median list price at an August 31, 2026 Realtor.com check, and Newton contributes something most of the county lacks: denser, walkable, in-town inventory — older single-family homes, condos, and legal multifamily stock. Sussex County also sits in NJHMFA's $10,000 down payment assistance tier, with income limits of $138,400 for 1-2 person and $159,160 for 3+ person households. Verify the exact address, legal use, and municipality first; Newton mailing addresses reach past the town line.
Continue your research
Compare the other Sussex County buyer guides
Real estate next step
Find and evaluate the right Newton, NJ home
Search current homes, then ask Ashley to help turn the most realistic addresses into showings, property questions, and an offer strategy.
Mortgage next step
Test the payment and loan plan against the home
Bring Jimmy the price, property type, estimated taxes, association details, cash plan, and timing. No approval or closing is promised.
General educational information only; not a commitment to lend. Program terms, approval, property eligibility, and closing are subject to current requirements and review. Equal Housing Opportunity.